ThermaLine Ice Melt Systems
Our heated panels are designed to safely eliminate snow and ice buildup before it becomes a problem.

Our heated panels are designed to safely eliminate snow and ice buildup before it becomes a problem.


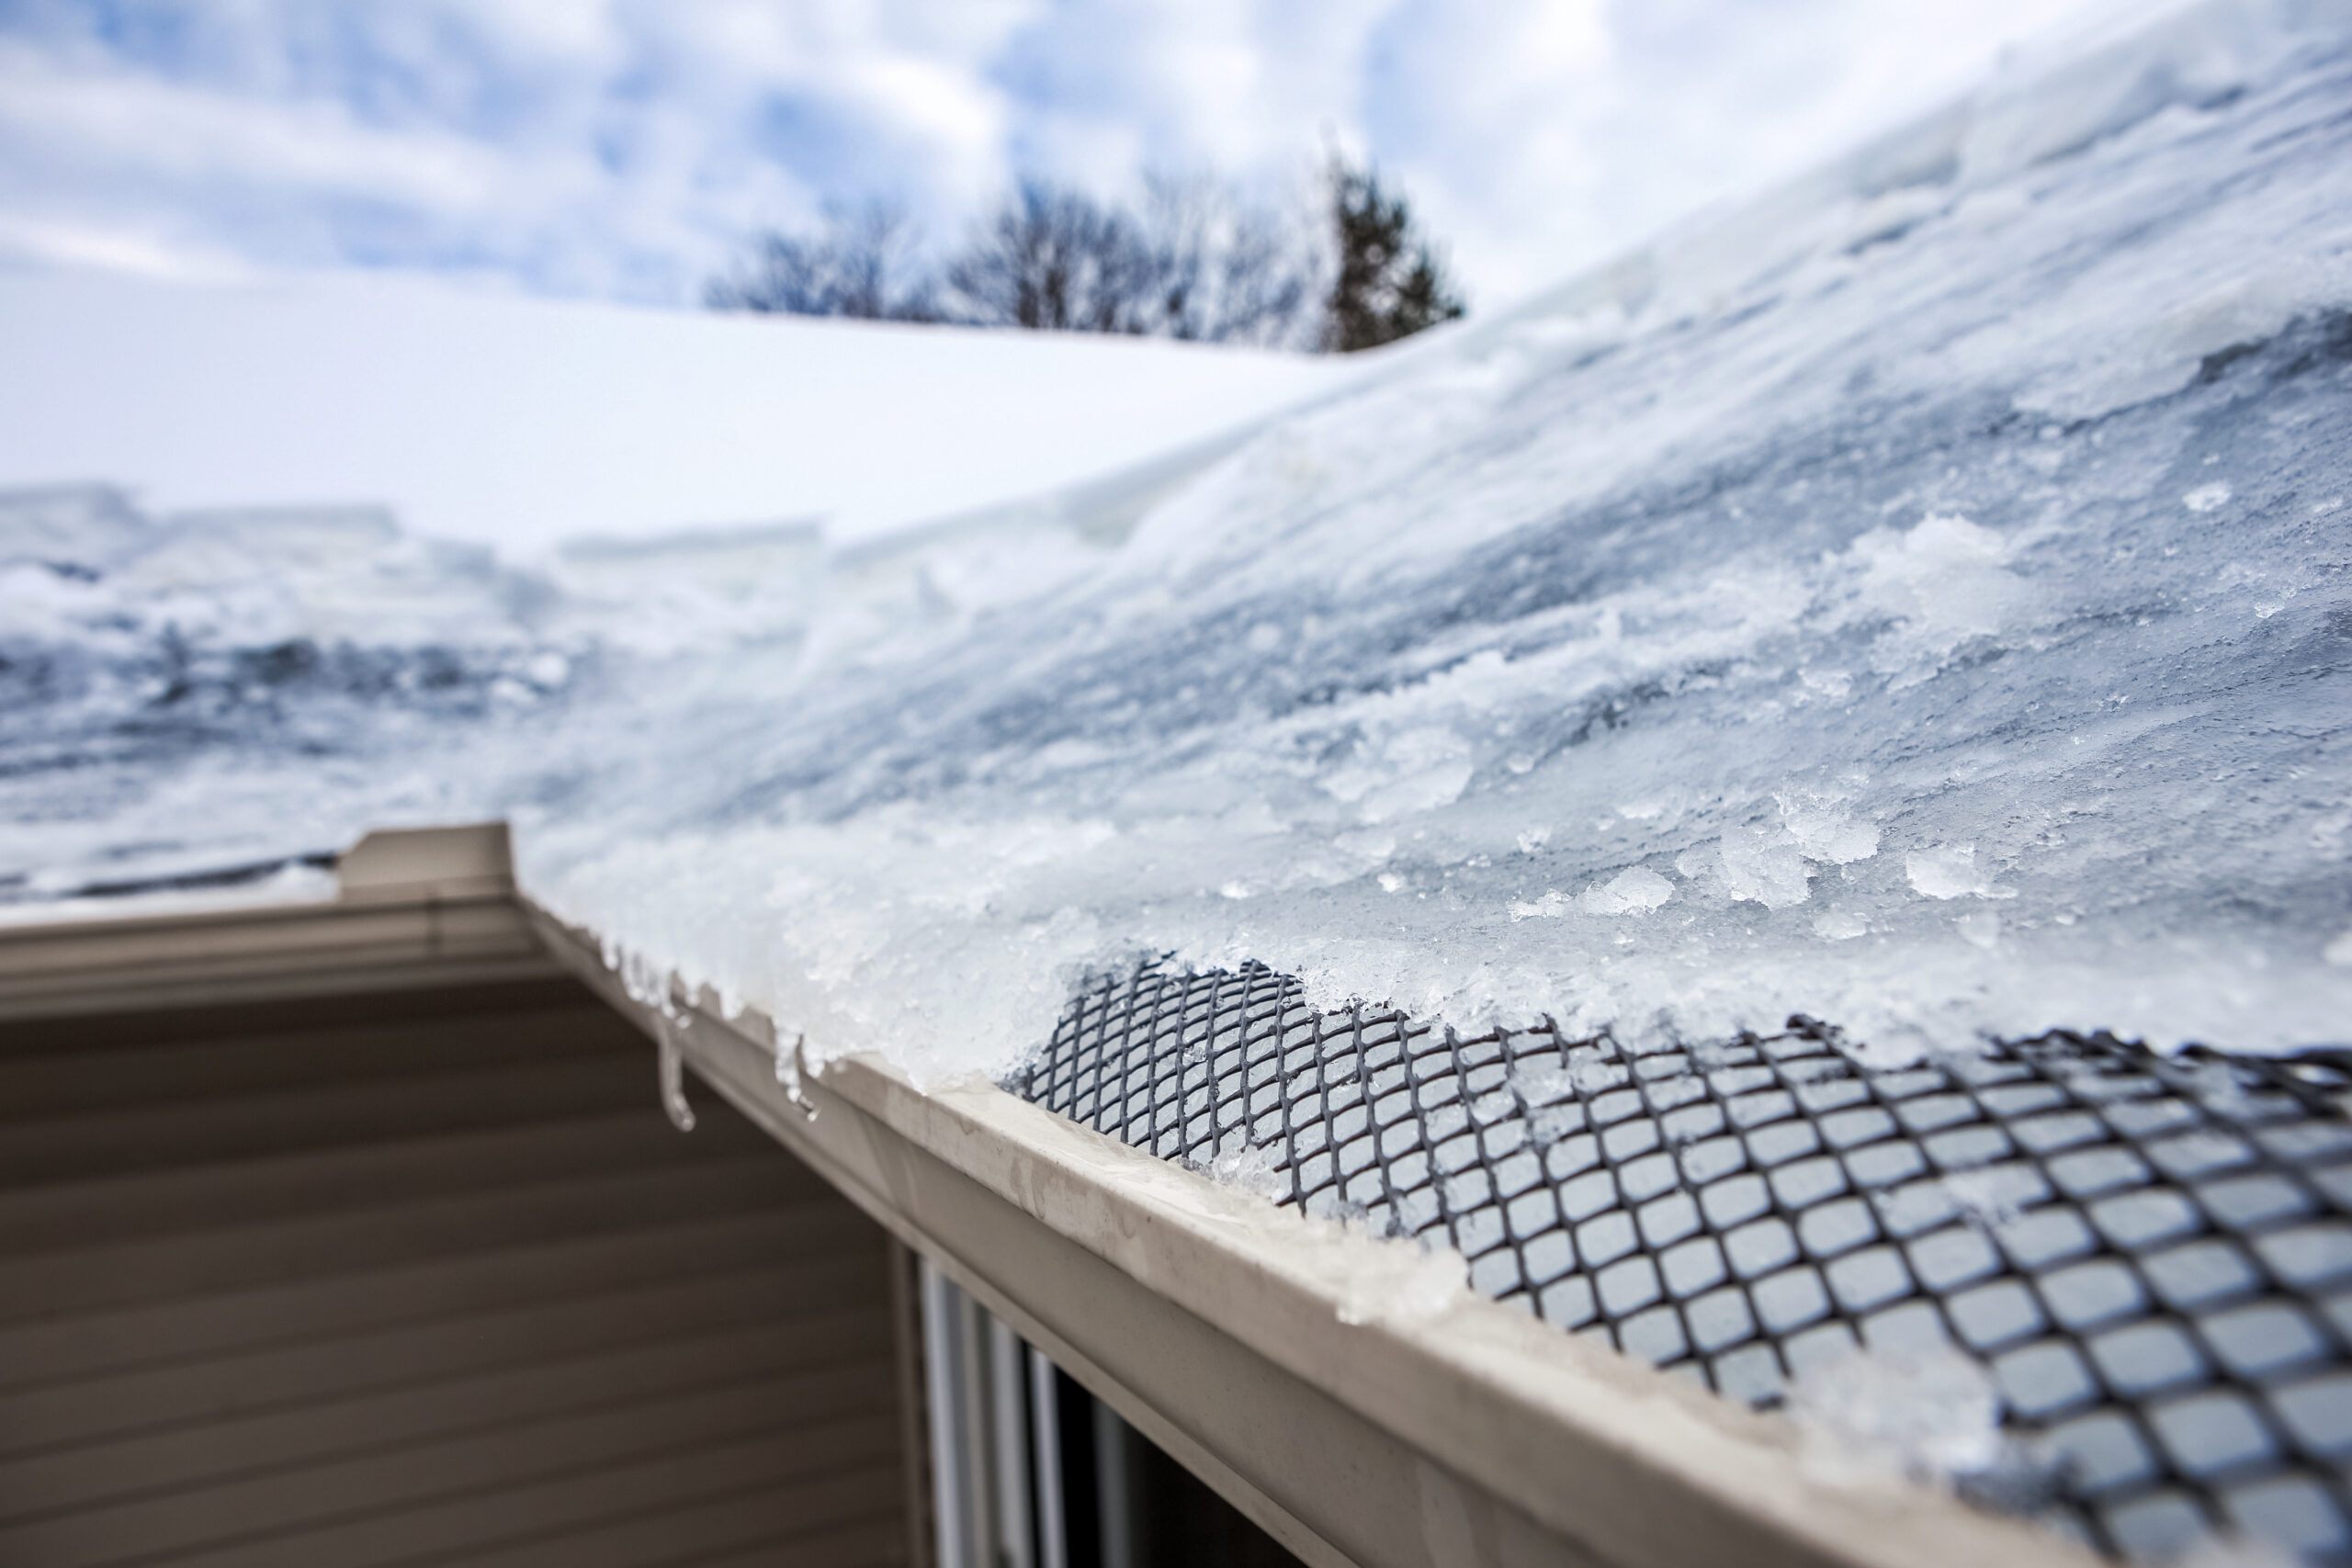
A leak appears above the ceiling grid in a leased suite on a February morning. Water tracks down an interior partition, soaks a section of carpet, and shorts a piece of equipment the tenant owns. Within a day the question stops being about roofing and becomes a three-way negotiation between the owner, the tenant and at least two insurance carriers.
That negotiation is rarely decided by who is at fault in any intuitive sense. It is decided by lease language written years earlier, by whose insurance policy covers which category of property, and by whether the owner can produce a maintenance record. Those three factors do most of the work, and the parties who prepared for them in advance do far better than the ones improvising in the middle of a loss.
ThermaLine builds roof ice melt systems, and the conversations that follow a tenant water loss are a recurring part of why owners call us. This article covers how responsibility typically gets allocated, what documentation strengthens an owner’s position, and why repeat claims change how carriers behave. It does not cover the physical mechanism of ice dam damage, which we address in how commercial ice dams cause expensive roof damage and liability risks.
This is general guidance, not legal advice. Lease interpretation is jurisdiction-specific and fact-specific, and the language in your actual lease governs. Have counsel review any real dispute and any lease you are drafting or negotiating.
Before the lease, it helps to understand the default architecture, because most commercial leases modify a version of it rather than inventing something new.
The owner typically holds responsibility for the roof, the structure and the building envelope, and insures the building itself. Where the owner’s failure to maintain those elements causes damage, the owner generally carries exposure for the consequences.
The tenant typically holds responsibility for the interior of the demised premises, insures its own property, and often insures tenant improvements and betterments depending on how the lease assigns them. The tenant also generally bears its own business interruption losses unless the lease or a specific policy provides otherwise.
The carriers pay according to their policies, not according to fairness. The owner’s property policy responds to building damage. The tenant’s policy responds to tenant property. The owner’s liability policy may respond if the tenant asserts the owner was negligent. Each carrier evaluates independently, and each will look for someone else to pay.
The complexity comes from the fact that a single ice dam leak usually damages property in more than one of these categories at once. The ceiling grid may be building property, the light fixture may be a tenant improvement, the inventory on the floor is tenant property, and the three days the space could not be used is business interruption. One event, four different answers.
When these disputes resolve, they resolve on lease language. Here are the provisions that carry the most weight, and what to look for in each.
Find the maintenance and repair article and read it carefully. Most commercial leases assign the roof and structure to the landlord, but the language varies in ways that matter. Watch for:
Gutters and drainage are the most commonly ambiguous items, and they are exactly where ice dam disputes concentrate. In a single-tenant industrial or retail lease it is not unusual for gutter maintenance to sit with the tenant while the roof sits with the landlord, which produces an unresolvable argument the moment ice backs up from a frozen gutter into the roof edge.
In a triple net or absolute net lease, particularly single-tenant industrial, the tenant may carry roof maintenance obligations that would sit with the landlord in a multi-tenant office building. Where that is the case, the analysis inverts, and the question becomes whether the tenant performed the maintenance it agreed to perform. Read the actual allocation rather than assuming based on property type.
Common area maintenance provisions determine whether the cost of preventing the problem can be passed through to tenants, and they usually distinguish between maintenance and capital improvements. A recurring snow and ice removal service is generally a maintenance expense and commonly passes through. A permanent installed system is more likely to be treated as a capital improvement, which may be excluded from pass-through entirely, may be amortized over its useful life, or may be permitted only in defined circumstances.
This matters more than it first appears. If the lease allows recurring reactive service to pass through but does not allow a permanent fix, the economics of the building push toward paying for the problem forever. Owners who notice this pattern often address it at lease renewal, either by permitting amortized capital pass-through or by treating the system as a landlord cost that reduces long-term exposure. That structural question is worth raising with counsel and with your asset manager well before a loss forces it.
Nearly every modern commercial lease contains an insurance article, and it typically does three things: it requires each party to carry specified coverage, it allocates which party insures which property, and it contains a mutual waiver of subrogation.
The waiver of subrogation is the provision most likely to determine the practical outcome, and it is the one most often overlooked by the people managing the loss. Where it applies, each party agrees that its own insurer will not pursue the other party for a loss covered by that insurance, even if the other party caused it. In effect, the parties agree in advance that insurance rather than litigation will resolve the covered portion of the loss.
Read it for scope. Some waivers cover all property damage. Some are limited to perils covered by required insurance. Some are conditioned on the policies actually containing the necessary endorsement, which means a party that failed to obtain the endorsement may not get the benefit.
Two categories cause repeated confusion:
Tenant improvements and betterments. Whether the landlord or the tenant insures these depends entirely on the lease. Getting this wrong is common, and it often surfaces for the first time during a claim, when both carriers point at each other. It is worth confirming for every space in the building before there is a loss, not after.
Business interruption. A tenant who cannot use the space generally looks to its own business interruption coverage. Whether the tenant can also seek rent abatement from the landlord depends on the lease’s untenantability or abatement provision, which typically defines a threshold of unusability and a waiting period. Whether the tenant can pursue the landlord for consequential losses beyond abatement depends on the indemnity and limitation of liability provisions, which frequently exclude consequential damages.
The table below reflects common allocations. It is a starting point for reading your lease, not a substitute for it, and any of these can be reallocated by contract.
| Damaged item | Commonly the responsibility of | What to verify in the lease |
|---|---|---|
| Roof membrane, deck, structure | Owner | Definition of “roof,” and whether to maintain or repair |
| Gutters, downspouts, drains | Varies significantly | Whether named explicitly or left to the general roof clause |
| Ceiling grid and tiles | Usually owner as building property | Whether the space was delivered with them or tenant-installed |
| Light fixtures, HVAC diffusers in the suite | Depends on original installation | Base building versus tenant improvement classification |
| Interior partitions and finishes | Usually tenant improvements | Who insures TI, per the insurance article |
| Flooring | Depends on whether base building or TI | Delivery condition and TI allowance records |
| Tenant inventory, equipment, furniture | Tenant | Tenant’s required property coverage |
| Data, records, product loss | Tenant | Tenant policy scope |
| Lost revenue during closure | Tenant business interruption | Abatement clause and consequential damages exclusion |
| Rent during unusable period | Governed by abatement provision | Tenantability threshold and waiting period |
Insurance mechanics resolve most of the covered property damage. What maintenance records affect is the harder territory: allegations of negligence, disputes over uncovered losses, carrier posture at renewal, and the owner’s leverage in the conversation.
An owner who can produce dated inspection reports, a record of identified conditions and the work performed in response is in a materially different position than one who cannot. The distinction that matters to carriers and to counsel is between a building where a known condition was managed and one where a known condition was ignored.
The strongest record includes:
That last item deserves emphasis. An owner who identified a recurring ice problem, submitted a capital request, and had it deferred by ownership is in a defensible position, because the record shows the condition was managed rather than ignored. An owner with no record at all has no story to tell. Our guide to reading a commercial roof in September for ice damage evidence covers how to build that documentation in a form that holds up later.
The inverse also holds. A tenant who reported a leak repeatedly, in writing, and received no response has built a record too. Notice provisions in leases usually require written notice for a reason, and both parties should treat email as the minimum standard.
A first ice dam claim is generally treated as a weather event. What changes the dynamic is repetition.
When the same location produces claims across multiple seasons, carriers begin to characterize the loss differently. The practical consequences owners report include closer scrutiny of the cause, requests for documentation of what has been done to address the condition, questions during renewal underwriting, and in some cases changes to deductibles, sublimits or specific exclusions related to water damage or ice. Carriers may also request evidence of corrective action as a condition of continued coverage on the same terms.
None of this is uniform, and it varies by carrier, market conditions and the specifics of the account. What is consistent is the underlying logic: insurance is priced for fortuitous events, and a condition that recurs predictably every winter starts to look less like a fortuity and more like a maintenance issue. Owners who can show a corrective plan in motion generally have an easier renewal conversation than owners who cannot.
The diagnostic meaning of recurrence is worth understanding on its own terms, because carriers and engineers reach the same conclusion from different directions. We cover it in why repeated ice dams on commercial buildings signal bigger drainage problems.
Subrogation is the mechanism by which an insurer that has paid a claim steps into its insured’s shoes and pursues whoever it believes caused the loss.
In practice, in a tenant ice dam loss, it looks like this. The tenant’s carrier pays the tenant for damaged property. The carrier then evaluates whether someone else is legally responsible. If it concludes the owner is, it may pursue the owner or the owner’s liability carrier to recover what it paid. The tenant is generally not a party to that recovery effort and may not even be aware of it.
Two things commonly stop this. The first is a waiver of subrogation in the lease, which, where enforceable and properly supported by policy endorsements, blocks the recovery action for covered losses. The second is a lack of evidence that the owner did anything wrong, which brings the analysis back to maintenance records.
Subrogation can also run the other direction, and it can involve third parties. If a snow removal contractor damaged the roof, or a roofing contractor’s work is implicated, carriers will look there as well. This is one reason vendor contracts, certificates of insurance and indemnity provisions are worth keeping current and on file.
What happens in the first 48 hours affects everything downstream.
Everything above describes how a loss gets resolved. The more useful question is what reduces the chance of having the conversation at all.
Three actions carry the most weight:
Documented seasonal inspection. It creates the record, and it identifies the condition early enough to act.
A written, funded plan for identified conditions. Even where the work has not happened yet, a plan that is documented and moving is materially better than a condition with no plan attached.
Removing the recurring cause. Where the same roof edge or valley ices every winter, the durable answer is to address the mechanism rather than the symptom. Engineered ice melt systems maintain a melt path so water leaves the roof instead of refreezing at the edge. ThermaLine panels hold UL-listed self-regulating heat trace cable in a raceway and install with commercial-grade adhesive without penetrating the roof deck, which matters when a roofing warranty is in play. Systems are UL listed and compliant with NEC Article 426 for roof deicing and carry a 10 year product warranty. Applications include eaves and overhangs, valleys, gutters and low-slope roof areas.
The comparison between preventing the condition and managing it reactively each winter is laid out in commercial ice dam prevention systems versus reactive winter maintenance, and it is the same analysis a carrier performs when it looks at a repeat claim.
It depends on the lease. Most commercial leases assign the roof, structure and envelope to the landlord and the interior of the demised premises to the tenant, with each party insuring its own property. Tenant improvements, gutters and snow removal are the items most often allocated differently from what people assume, so the lease language controls rather than the general pattern.
Usually both, for different categories of property. The landlord’s property policy generally responds to building damage, and the tenant’s policy generally responds to tenant property and often to tenant improvements, depending on how the lease assigns them. Business interruption is typically the tenant’s own coverage. Confirm the allocation in the insurance article of the lease.
It is a lease provision in which each party agrees that its insurer will not pursue the other party to recover a loss covered by insurance, even if that party caused it. Where it applies and the policies contain the necessary endorsement, it typically resolves the covered portion of the loss through insurance rather than through a claim between the parties.
Only as the lease permits. Most commercial leases contain an abatement or untenantability provision that defines when rent abates, what threshold of unusability triggers it, and whether a waiting period applies. Withholding rent outside those provisions generally creates a separate default issue, so this should be reviewed with counsel before any action.
They distinguish a building where a known condition was managed from one where it was ignored. Dated inspections, written findings, evidence of response, vendor records and documented remediation planning strengthen an owner’s position in negligence allegations, uncovered-loss disputes and insurance renewal conversations. A capital request that was submitted and deferred still counts as management.
Carriers commonly begin scrutinizing repeat losses more closely, asking what corrective action has been taken, and revisiting terms at renewal. Outcomes vary by carrier and market, but the underlying logic is consistent: a condition that recurs predictably is treated less like a fortuitous event and more like a maintenance issue. Documented corrective action generally helps that conversation.
That depends on the CAM provisions and how they treat capital improvements. Recurring snow and ice service is commonly treated as maintenance and often passes through, while permanent installed systems may be excluded, amortized, or permitted only in defined circumstances. Review the actual language with counsel, and consider addressing it at renewal if the current structure makes prevention harder to fund than repetition.
An ice dam loss in a tenant space becomes a dispute because three documents that were written at different times, by different people, for different purposes, have to be reconciled under time pressure while someone’s business is disrupted. The owners who come out of it well are the ones who read the lease before the loss, confirmed who insures what, kept a maintenance record, and had a plan in motion for the condition everyone already knew about.
The most durable version of that plan removes the recurring cause. If the same roof edge, valley or gutter run has produced a claim more than once, contact ThermaLine with your roof details and loss history. We can help you evaluate what an engineered ice melt system would involve, and provide the product, listing and warranty documentation your risk manager and your carrier will ask for.